Jumbo Loan for South Florida Luxury Homes: How Weston Buyers Finance Above Conforming Limits
Last Updated: November 2026
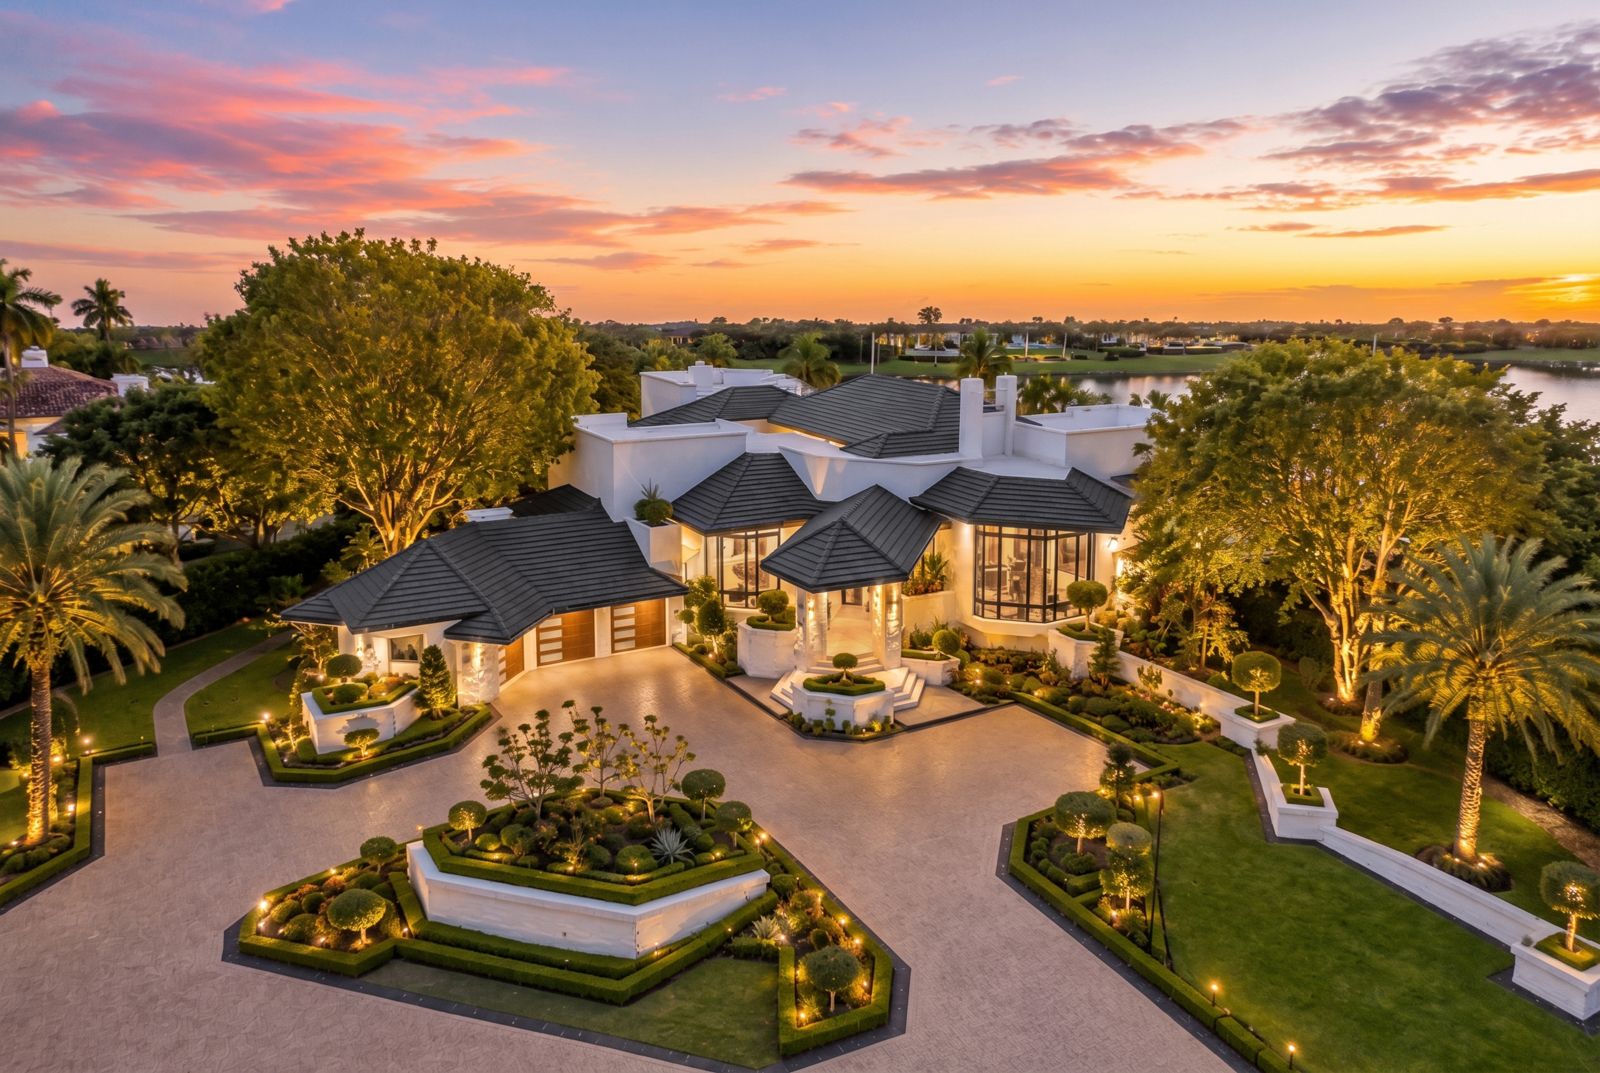
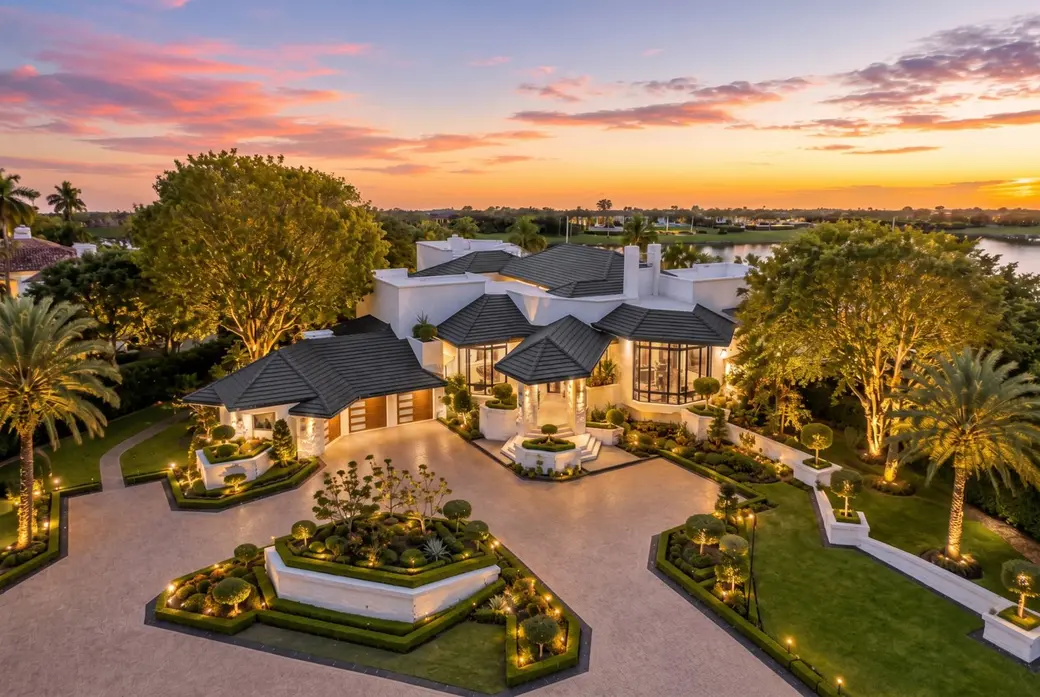
Broward County's conforming loan limit for 2026 is $832,750. (Source: JVM Lending Florida Conforming Loan Limits, 2026) In Weston, the average single family home closed at $1,058,208 in the fourth quarter of 2025. (Source: Miller Samuel Weston Q4 2025 Report, Jan 2026) With a standard 20 percent down payment, an average priced Weston purchase lands in jumbo territory before you tour a single home. That is why a jumbo loan for South Florida luxury homes is worth understanding before you fall for one.
Many luxury buyers here choose to finance rather than pay cash, and a jumbo loan is the tool that makes it work. Luxury sales also climbed sharply across the state in early 2026. (Source: Florida Realtors, May 2026) Lately I've been noticing that the buyers who struggle are rarely short on money. They are short on preparation. This guide explains how jumbo financing works, what lenders ask for, and how a financed buyer competes with cash across Weston and Southwest Ranches.
Quick Answer: What Is a Jumbo Loan for South Florida Luxury Homes?
A jumbo loan for South Florida luxury homes is any mortgage above the $832,750 Broward conforming limit. Most lenders expect 10 to 20 percent down, a credit score near 700 or higher, and six to twelve months of reserves. Well documented buyers can still compete with cash offers.
KEY TAKEAWAYS
- Broward County's 2026 conforming limit is $832,750, so any mortgage above that amount is a jumbo loan.
- Most jumbo lenders look for a 700 or higher credit score, 10 to 20 percent down, and six to twelve months of reserves.
- A larger down payment can pull a Weston purchase back under the conforming line, which changes the loan type and the underwriting path.
- Cash made up 37.1% of Broward sales in June 2026, so the majority of buyers were not paying cash.
- Jumbo closings can run longer, so a lender who has already reviewed your file matters as much as the rate.
IN THIS GUIDE
- What Is a Jumbo Loan for South Florida Luxury Homes, and Where Does the Line Sit in Broward?
- Why Weston and Southwest Ranches Buyers Cross the Line So Often
- What Jumbo Lenders Actually Ask For in Broward County
- Down Payment, Reserves, and Rates: What Jumbo Financing Really Costs
- How Financed Buyers Compete With Cash in South Florida Luxury
- Build Your Financing Plan Before You Tour
- The Quiet Advantage of Preparing Early
- Frequently Asked Questions
What Is a Jumbo Loan for South Florida Luxury Homes, and Where Does the Line Sit in Broward?
A jumbo loan is a mortgage larger than the conforming limit the Federal Housing Finance Agency sets each year. Fannie Mae and Freddie Mac cannot purchase or guarantee loans above that limit, so the lender carries more risk and applies stricter standards. (Source: Chase, 2026)
For 2026, the baseline limit rose to $832,750, which is $26,250 higher than the year before. (Source: South Florida Agent Magazine, Aug 2026) Monroe County is Florida's only high cost county, with a one unit cap of $990,150, so Broward County sits at the baseline. (Source: Florida Realtors, Nov 2025) FHFA announces the next year's limits each November, so these figures may change for 2027.
WHAT IS A JUMBO LOAN?
A jumbo loan is a mortgage that exceeds the FHFA conforming limit for the county where the home is located. In Broward County, that means any single family loan above $832,750 in 2026.
One thing buyers are sometimes surprised by: the limit applies to the loan, not the price. A $1,040,000 purchase with 20 percent down creates an $832,000 loan, just under the line. At $1,100,000 with the same down payment, the loan becomes $880,000, and the rules change.
Why Weston and Southwest Ranches Buyers Cross the Line So Often
The Weston numbers explain it. The average single family sale in the fourth quarter of 2025 was $1,058,208, down 2.4% from the year before. (Source: Miller Samuel Weston Q4 2025 Report, Jan 2026) With 20 percent down, that purchase creates a loan of roughly $846,566, above the conforming limit. With 25 percent down, the loan falls to about $793,656, back under it. Same house, different loan type, different underwriting path.
Weston is not one uniform price band, so buyers at the lower end of the market often stay comfortably inside conforming limits. From what I'm seeing, the jumbo conversation usually begins in the gated golf and lake communities, which you can explore through our Weston community guide.
In Southwest Ranches the equation shifts again. Acreage, equestrian infrastructure, and custom construction push many purchases well above the conforming line, and lenders look at the property itself more carefully. Our Southwest Ranches community guide shows the range of estates buyers are weighing.
What Jumbo Lenders Actually Ask For in Broward County
Every lender sets its own guidelines, but the pattern is consistent. You will likely need a credit score of at least 700 or 720. (Source: SoFi, 2026) Jumbo lenders prefer a debt to income ratio of 43 percent or below, and they typically require six to twelve months of mortgage payments in reserve after closing. (Source: Direct Lender, 2026) Reserves are the item buyers underestimate, because they sit beyond the down payment and closing costs.
The appraisal also gets more attention. Jumbo investors often require a second review of the appraisal, and sometimes a second full appraisal. One lender quotes its fastest jumbo closings at 17 to 21 days, against 12 to 14 for conforming loans, which shows how much extra review can add. (Source: JVM Lending, 2026)
A jumbo loan is not harder because lenders want to say no. It is harder because they cannot pass the risk to Fannie Mae or Freddie Mac.
Jumbo vs Conforming in Broward County
| Feature | Conforming Loan | Jumbo Loan |
|---|---|---|
| Loan amount in Broward | Up to $832,750 | Above $832,750 |
| Typical down payment | As low as 3% on some programs | 10% to 20% |
| Typical debt to income | 45% to 50% allowed | 43% or below preferred |
| Cash reserves after closing | 0 to 2 months | 6 to 12 months |
| Appraisal | Standard appraisal | Often a second review or appraisal |
Source: Direct Lender Jumbo Loans Explained, 2026. Down payment ranges: Credible. Appraisal: JVM Lending.
Down Payment, Reserves, and Rates: What Jumbo Financing Really Costs
Most lenders ask for 10 to 20 percent down on a jumbo loan. (Source: Credible, 2026) Putting more down usually earns better pricing, and it can pull the loan back under the conforming limit.
Rates are the headline everyone watches. The Freddie Mac 30 year fixed average was 7.32% on October 22, 2026, down from 7.40% the week before and well above the 6.19% average a year earlier. (Source: Freddie Mac Primary Mortgage Market Survey, Oct 2026) Jumbo rates have generally run slightly above 30 year rates, though the two move roughly in tandem. (Source: LendingTree, 2026)
Honestly, I would treat the rate as one line item. Lender fees, reserve requirements, appraisal costs, and rate lock terms shape the real cost of the loan as much as the quoted number.
How Financed Buyers Compete With Cash in South Florida Luxury
Cash is part of every luxury negotiation here, but it is not the whole story. Cash represented 37.1% of Broward closed sales in June 2026, up from 36.6% a year earlier. (Source: MIAMI REALTORS + RWorld, Jul 2026) Among million dollar single family sales in Broward in 2025, cash buyers accounted for 41%. (Source: MIAMI REALTORS Southeast Florida Luxury Sales Report 2025, Feb 2026) Closer to home, Weston single family buyers used a mortgage in 77.3% of Q4 2025 sales, up from 74.5% a year earlier. (Source: Miller Samuel Weston Q4 2025 Report, Jan 2026)
Jumbo Financing Snapshot: Broward and Weston
| Market Metric | Current | Comparison |
|---|---|---|
| Broward conforming limit, 2026 | $832,750 | $806,500 in 2025 |
| 30 year fixed rate, Oct 22, 2026 | 7.32% | 6.19% a year earlier |
| Cash share of Broward closed sales, June 2026 | 37.1% | 36.6% in June 2025 |
| Cash share of Broward million dollar single family sales, 2025 | 41% | 52% across Southeast Florida |
| Weston single family average sale price, Q4 2025 | $1,058,208 | $1,083,928 in Q4 2024 |
| Weston single family sales using a mortgage, Q4 2025 | 77.3% | 74.5% in Q4 2024 |
Source: MIAMI REALTORS + RWorld Broward County Report, Jul 2026. Other rows: Florida Realtors, Freddie Mac, MIAMI REALTORS Southeast Florida Luxury Sales Report 2025, and Miller Samuel.
Across South Florida, million dollar sales rose 21.9% year to date through June 2026, and cash accounted for 61% of them. (Source: MIAMI REALTORS South Florida Million Dollar Sales, Jul 2026) The competition is real. It is also manageable.
If you are weighing a purchase above the conforming line, our signature buying process shows how we coordinate lender introductions, offer strategy, and timing before you ever submit an offer.
The question I get most often about this is whether financing weakens an offer. It can, when the paperwork is thin. When the file is complete, sellers tend to focus on price and certainty. A financed offer reads closer to cash when it includes:
- A full preapproval with income, assets, and credit reviewed, not a quick prequalification letter.
- A lender who closes jumbo loans regularly and can explain the appraisal process.
- Documents already organized: tax returns, bank and investment statements, and proof of reserves.
- A plan for an appraisal that comes in below the contract price.
- Closing timing that reflects a realistic jumbo timeline.
Build Your Financing Plan Before You Tour
Start with the line. Decide whether you want a loan under $832,750 or whether a jumbo structure suits your cash position better. Your down payment is the lever that moves you between the two.
Then speak with two or three lenders, not one. Compare reserve requirements, appraisal policies, closing timelines, and total fees next to the quoted rate. Ask each one how many jumbo loans they closed recently in Broward County, and ask who handles the file when questions come up mid contract.
At Dluxuss Group, we walk buyers through this before a showing is scheduled, because an offer built on a finished file is calmer for everyone involved. Our piece on why luxury buyers in Weston are more patient than ever explains how that patience changes negotiations, and current real estate trends in Weston gives broader context on pricing and timing. You can learn more about our team at Dluxuss Group.
The Quiet Advantage of Preparing Early
The loan type rarely decides who wins a luxury home. Preparation does. A buyer who understands the $832,750 line, has reviewed the file with a lender, and holds reserves in the right place can make an offer that reads as confident rather than conditional.
I am a real estate advisor, not a lender, so I always encourage buyers to confirm their own numbers with a licensed mortgage professional. If you are considering a purchase in Weston or Southwest Ranches, request a private lender introduction and financing consultation. We will connect you with lenders who finance homes in these communities regularly and walk through the process with no pressure.
ABOUT THE AUTHOR
Denice Landaeta is a top-ranked luxury real estate agent in Weston, Florida, and the founder of Dluxuss Group, a luxury, business, and commercial real estate boutique within the Coldwell Banker Global brand. With 15 years of experience as a real estate business developer and franchise professional, she has closed more than 800 transactions in the last eight years across Weston, Southwest Ranches, Parkland, and South Florida.
Denice ranks #139 nationwide on the RealTrends and The Wall Street Journal America's Best list and is a NAHREP Top 100 Latino Agent nationally for four consecutive years, reaching #32 in 2023 out of 28,000 nominated agents. She is a Coldwell Banker Top Producer since 2013, a President's Circle member, and holds the CLHMS, Million Dollar GUILD, and Global Luxury Specialist designations, credentials that place her among the top luxury real estate specialists in South Florida.
Denice is active in her community, having awarded scholarships to local high school seniors and supported the Ronald McDonald House Charities of Miami.
Licensed Realtor® · Florida License #SL3364483 · Coldwell Banker Realty
Frequently Asked Questions
Can you use a jumbo loan to buy a luxury home in South Florida?
Yes. A jumbo loan is the standard financing route when a mortgage exceeds the conforming limit, which is $832,750 in Broward County for 2026. Lenders set their own guidelines, so approval depends on credit, income, reserves, and the property. A full preapproval before you tour shows you what is realistic.
What qualifies as a jumbo loan in Florida?
A jumbo loan is any mortgage above the FHFA conforming limit for the county. Most Florida counties, including Broward and Miami Dade, use the 2026 baseline of $832,750, while Monroe County, the state's only high cost county, has a one unit cap of $990,150. The limit applies to the loan amount, not the purchase price. (Source: Florida Realtors, Nov 2025)
How much down payment do you need for a jumbo loan in Florida?
Most lenders ask for 10 to 20 percent down. (Source: Credible, 2026) Putting more down usually earns better pricing and can bring the loan back under the conforming limit.
Are jumbo loan rates higher than conventional rates?
Jumbo rates have generally run slightly above conforming rates, though the two tend to move in the same direction. (Source: LendingTree, 2026) Borrowers with strong credit and larger down payments may find pricing closer to conforming levels. For reference, the Freddie Mac 30 year fixed average was 7.32% on October 22, 2026. (Source: Freddie Mac, Oct 2026)
What are the jumbo loan requirements in Broward County?
Most lenders look for a credit score of at least 700. (Source: SoFi, 2026) They also look for a debt to income ratio near 43 percent or lower and six to twelve months of cash reserves after closing. (Source: Direct Lender, 2026) Some require a second appraisal or review, so compare two or three lenders before you decide.
Can a financed buyer compete with an all cash offer in Weston?
Yes, particularly with a fully underwritten preapproval and a lender who closes jumbo loans regularly. Cash represented 37.1% of Broward closed sales in June 2026, so most buyers were not paying cash. (Source: MIAMI REALTORS + RWorld, Jul 2026) Clean documentation and realistic timing matter as much as price.
Will a jumbo loan require a second appraisal?
Not always, but some lenders require a second appraisal or an additional review on higher priced properties. (Source: JVM Lending, 2026) A second appraisal adds cost and time, so ask your lender about it early. Building that time into your offer keeps the closing date realistic.
Who is Denice Landaeta?
Denice Landaeta is a luxury real estate advisor and founder of Dluxuss Group in Weston, Florida, ranked #139 nationally on the RealTrends and Wall Street Journal America's Best list and a NAHREP Top 100 Latino Agent nationally for four consecutive years.
Categories
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "